

Revenue Recognition for Construction Contractors: Cash vs. Accrual, PCM, and the Accrual‑to‑Cash Impact
Revenue recognition for construction contractors is governed by a unique tax framework that is often misunderstood. Contractors must navigate two distinct sets of accounting rules: the overall tax accounting method (cash, accrual, or hybrid) and the long-term contract accounting requirements of Section 460. Because these rules operate concurrently, they can significantly affect taxable income, cash flow, and the timing of revenue recognition, often creating substantial year-to-year fluctuations between book income and taxable income. Understanding the interaction between these rules is critical for sound tax planning, compliance, and financial decision-making.
1. Overall Methods vs. Contract Methods
Two sets of rules affect a contractor:
- Overall accounting method (cash, accrual, or hybrid) under tax code §446 and §448.
- Long‑term contract method (Percentage of completion method (PCM), completed‑contract, exempt PCM) under tax code §460.
An exception from PCM does not automatically authorize the cash method. Eligibility for cash depends on the small‑business gross‑receipts test and other limitations.
2. Cash and Accrual Methods in Practice
Cash method
Under the cash receipts and disbursements method, income is generally recognized when received and expenses when paid.
For a contractor:
- Customer collections (including retainage) are income when received.
- Job costs are deducted when paid, subject to capitalization rules.
- Uncollected receivables and unpaid accruals usually do not affect taxable income until cash changes hands.
Use of the cash method is limited. Corporations and certain partnerships, and businesses exceeding the inflation‑adjusted gross‑receipts threshold, may be barred from using cash accounting. Inventory and uniform capitalization rules can also require capitalization of certain direct and indirect costs even for cash‑method taxpayers.
Accrual method
Under an accrual method, revenue is recognized when the right to receive it is fixed and the amount is determinable, and expenses when the liability is fixed and economic performance occurs. For non‑§460 contracts, this typically means recognizing contract revenue as performance obligations are satisfied or as the taxpayer has an enforceable right to payment.
If a contract is a long‑term construction contract under §460, then PCM or another permitted long‑term contract method governs income recognition, not a general accrual method alone.
3. Long‑Term Construction Contracts and Key Exceptions
A contract is a long‑term construction contract if it involves building, installation, or construction of real property and is not completed in the year it is entered into. Section 460 generally requires PCM based on a cost‑to‑cost percentage.
Percentage of Completion Method (PCM)
PCM requires the recognition of income as work progresses rather than waiting until the contract is finished.
Under §460(b), the degree of completion is typically determined by the “cost-to-cost” method, which follows these steps:
- Determine the Completion Factor: Divide the total allocable contract costs incurred through the end of the year by the total estimated allocable contract costs.
- Calculate Cumulative Gross Receipts: Multiply the completion factor by the total estimated contract price. The contract price includes the original amount plus change orders, retainages, and contingent compensation (like bonuses or awards) that the taxpayer reasonably expects to receive.
- Determine Current Year Income: Subtract the cumulative gross receipts reported in all prior years from the current cumulative gross receipts.
Exempt construction contracts
Certain contracts are exempt from mandatory PCM:
- Home construction contracts – 80%+ of total estimated contract costs relate to dwelling units in buildings with four or fewer units and directly related on‑site improvements.
- Small construction contracts – contracts expected at inception to finish within two years and performed by taxpayers (other than tax shelters) that meet the small‑business gross‑receipts test of §448(c) for the year the contract is entered into.
- Residential construction contracts entered into in tax years beginning after July 4, 2025– these contracts must also meet the 80% cost test for dwelling units, but the building or buildings constructed contain more than four units (e.g., a large apartment complex).
For these exempt contracts, the contractor may use:
- Completed‑contract method (CCM)– income and costs reported when the contract is completed (typically when 95% of costs are incurred and the customer can use the property).
- Exempt‑contract PCM (EPCM) – Instead of the rigid cost-to-cost method, completion can be measured by comparing direct labor costs to total estimated labor, or by “work performed” (output methods like units-of-delivery or miles of road completed), provided the method is used consistently and clearly reflects income.
- Any other permissible method, such as cash or accrual, if otherwise allowed under §§446 and 448.
These exemptions remove the PCM requirement for the specific contracts but do not override cash‑method limitations, inventory, capitalization, or depreciation rules.
4. Accrual‑to‑Cash Conversion: Why the Numbers Can Shift Dramatically
When a contractor maintains its books on GAAP basis, but files a cash-basis tax return, taxable income can diverge sharply from book income. A common recurring adjustment converts accrual-basis book income to cash‑basis taxable income.
Assume:
- The contractor is eligible for the cash method.
- 2025 books are kept on accrual.
- Accounts receivable (A/R) are revenue recognized but not yet collected.
- Accounts payable (A/P) are deductible expenses accrued but not yet paid.
- Other book‑to‑tax differences (inventory, §263A, contract‑method timing, depreciation, prepaid items) are either not present or separately reconciled.
A simple reconciliation is:
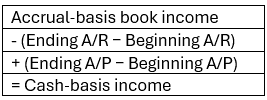
Interpretation:
- If A/R increases, subtract the increase: accrual income exceeds cash collections.
- If A/R decreases, add the decrease: cash collections exceed current‑year accrual revenue.
- If A/P increases, add the increase: accrual expenses exceed cash payments.
- If A/P decreases, subtract the decrease: cash payments exceed current‑year accrual expenses.
This is a timing adjustment. Reducing taxable income by $150,000 does not reduce tax by $150,000; the tax impact depends on rates and other limitations.
5. Short Example: 2024–2025 Accrual‑to‑Cash Impact
Assume a contractor:
- Files their tax return on cash-basis.
- Keeps 2024 and 2025 books on accrual.
- Has no other book‑to‑tax differences beyond A/R and A/P.
Balance‑sheet data
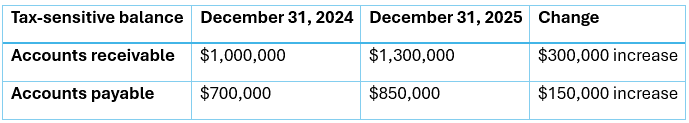
Accrual‑basis book income for 2025 is $600,000.
Cash‑basis income = $600,000 − $300,000 + $150,000 = $450,000
Here, taxable income on the cash method is $150,000 lower than accrual‑basis book income—even before considering other common differences like retainage, unbilled work, contract assets, deferred revenue, capitalized costs, and prepaid items.
For construction contractors, a more robust schedule should separately track billed and unbilled receivables, retainage, inventory, contract assets, deferred revenue, accrued job costs, stored materials, prepaid costs, and capitalized contract costs. The simple A/R and A/P reconciliation is appropriate only when these other items are either absent or reconciled under the chosen tax method.
6. Practical Takeaways for CPAs and Contractors
- Separate the overall method (cash vs. accrual) from long‑term contract methods (PCM, CCM, EPCM).
- Evaluate small‑contract and home/residential construction exceptions contract‑by‑contract at inception; they can open the door to CCM or exempt PCM and influence timing of revenue recognition.
- For eligible small contractors, consider whether the cash method better aligns taxable income with cash flow, but model the impact of A/R and A/P (and contract‑specific balances) before recommending a change.
- If you have GAAP basis financials and cash-basis tax return, plan for an ongoing annual accrual‑to‑cash adjustment.
The composition of a contractor’s balance sheet at year-end can have a significant impact on taxable income. Changes in receivables, payables, retainage, and other contract-related accounts often drive substantial differences between book income and taxable income. As a result, maintaining a clear understanding of both projected taxable income and the expected accrual-to-cash adjustment is critical for effective tax planning and avoiding year-end surprises.

 Food Cost Percentage