Revenue Recognition for Construction Contractors: Cash vs. Accrual, PCM, and the Accrual‑to‑Cash Impact

Revenue Recognition for Construction Contractors: Cash vs. Accrual, PCM, and the Accrual‑to‑Cash Impact


Revenue recognition for construction contractors is governed by a unique tax framework that is often misunderstood. Contractors must navigate two distinct sets of accounting rules: the overall tax accounting method (cash, accrual, or hybrid) and the long-term contract accounting requirements of Section 460. Because these rules operate concurrently, they can significantly affect taxable income, cash flow, and the timing of revenue recognition, often creating substantial year-to-year fluctuations between book income and taxable income. Understanding the interaction between these rules is critical for sound tax planning, compliance, and financial decision-making.


1. Overall Methods vs. Contract Methods

Two sets of rules affect a contractor:

  • Overall accounting method (cash, accrual, or hybrid) under tax code §446 and §448.
  • Long‑term contract method (Percentage of completion method (PCM), completed‑contract, exempt PCM) under tax code §460.

An exception from PCM does not automatically authorize the cash method. Eligibility for cash depends on the small‑business gross‑receipts test and other limitations.


2. Cash and Accrual Methods in Practice

Cash method

Under the cash receipts and disbursements method, income is generally recognized when received and expenses when paid.

For a contractor:

  • Customer collections (including retainage) are income when received.
  • Job costs are deducted when paid, subject to capitalization rules.
  • Uncollected receivables and unpaid accruals usually do not affect taxable income until cash changes hands.

Use of the cash method is limited. Corporations and certain partnerships, and businesses exceeding the inflation‑adjusted gross‑receipts threshold, may be barred from using cash accounting. Inventory and uniform capitalization rules can also require capitalization of certain direct and indirect costs even for cash‑method taxpayers.

Accrual method

Under an accrual method, revenue is recognized when the right to receive it is fixed and the amount is determinable, and expenses when the liability is fixed and economic performance occurs. For non‑§460 contracts, this typically means recognizing contract revenue as performance obligations are satisfied or as the taxpayer has an enforceable right to payment.

If a contract is a long‑term construction contract under §460, then PCM or another permitted long‑term contract method governs income recognition, not a general accrual method alone.


3. Long‑Term Construction Contracts and Key Exceptions

A contract is a long‑term construction contract if it involves building, installation, or construction of real property and is not completed in the year it is entered into. Section 460 generally requires PCM based on a cost‑to‑cost percentage. 

Percentage of Completion Method (PCM)

PCM requires the recognition of income as work progresses rather than waiting until the contract is finished.

Under §460(b), the degree of completion is typically determined by the “cost-to-cost” method, which follows these steps:

  1. Determine the Completion Factor: Divide the total allocable contract costs incurred through the end of the year by the total estimated allocable contract costs.
  2. Calculate Cumulative Gross Receipts: Multiply the completion factor by the total estimated contract price. The contract price includes the original amount plus change orders, retainages, and contingent compensation (like bonuses or awards) that the taxpayer reasonably expects to receive.
  3. Determine Current Year Income: Subtract the cumulative gross receipts reported in all prior years from the current cumulative gross receipts.

Exempt construction contracts

Certain contracts are exempt from mandatory PCM:

  • Home construction contracts – 80%+ of total estimated contract costs relate to dwelling units in buildings with four or fewer units and directly related on‑site improvements.
  • Small construction contracts – contracts expected at inception to finish within two years and performed by taxpayers (other than tax shelters) that meet the small‑business gross‑receipts test of §448(c) for the year the contract is entered into.
  • Residential construction contracts entered into in tax years beginning after July 4, 2025– these contracts must also meet the 80% cost test for dwelling units, but the building or buildings constructed contain more than four units (e.g., a large apartment complex).

For these exempt contracts, the contractor may use:

  • Completed‑contract method (CCM)– income and costs reported when the contract is completed (typically when 95% of costs are incurred and the customer can use the property).
  • Exempt‑contract PCM (EPCM) – Instead of the rigid cost-to-cost method, completion can be measured by comparing direct labor costs to total estimated labor, or by “work performed” (output methods like units-of-delivery or miles of road completed), provided the method is used consistently and clearly reflects income.
  • Any other permissible method, such as cash or accrual, if otherwise allowed under §§446 and 448.

These exemptions remove the PCM requirement for the specific contracts but do not override cash‑method limitations, inventory, capitalization, or depreciation rules.


4. Accrual‑to‑Cash Conversion: Why the Numbers Can Shift Dramatically

When a contractor maintains its books on GAAP basis, but files a cash-basis tax return, taxable income can diverge sharply from book income. A common recurring adjustment converts accrual-basis book income to cash‑basis taxable income.

Assume:

  • The contractor is eligible for the cash method.
  • 2025 books are kept on accrual.
  • Accounts receivable (A/R) are revenue recognized but not yet collected.
  • Accounts payable (A/P) are deductible expenses accrued but not yet paid.
  • Other book‑to‑tax differences (inventory, §263A, contract‑method timing, depreciation, prepaid items) are either not present or separately reconciled.

A simple reconciliation is:
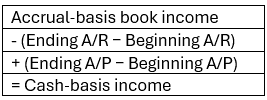
Interpretation:

  • If A/R increases, subtract the increase: accrual income exceeds cash collections.
  • If A/R decreases, add the decrease: cash collections exceed current‑year accrual revenue.
  • If A/P increases, add the increase: accrual expenses exceed cash payments.
  • If A/P decreases, subtract the decrease: cash payments exceed current‑year accrual expenses.

This is a timing adjustment. Reducing taxable income by $150,000 does not reduce tax by $150,000; the tax impact depends on rates and other limitations.


5. Short Example: 2024–2025 Accrual‑to‑Cash Impact

Assume a contractor:

  • Files their tax return on cash-basis.
  • Keeps 2024 and 2025 books on accrual.
  • Has no other book‑to‑tax differences beyond A/R and A/P.

Balance‑sheet data
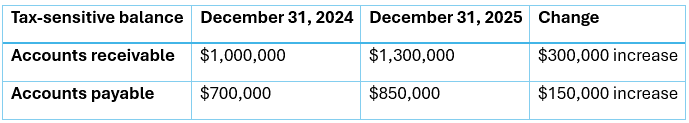
Accrual‑basis book income for 2025 is $600,000.

Cash‑basis income = $600,000 − $300,000 + $150,000 = $450,000

Here, taxable income on the cash method is $150,000 lower than accrual‑basis book income—even before considering other common differences like retainage, unbilled work, contract assets, deferred revenue, capitalized costs, and prepaid items.

For construction contractors, a more robust schedule should separately track billed and unbilled receivables, retainage, inventory, contract assets, deferred revenue, accrued job costs, stored materials, prepaid costs, and capitalized contract costs. The simple A/R and A/P reconciliation is appropriate only when these other items are either absent or reconciled under the chosen tax method.


6. Practical Takeaways for CPAs and Contractors

  • Separate the overall method (cash vs. accrual) from long‑term contract methods (PCM, CCM, EPCM).
  • Evaluate small‑contract and home/residential construction exceptions contract‑by‑contract at inception; they can open the door to CCM or exempt PCM and influence timing of revenue recognition.
  • For eligible small contractors, consider whether the cash method better aligns taxable income with cash flow, but model the impact of A/R and A/P (and contract‑specific balances) before recommending a change.
  • If you have GAAP basis financials and cash-basis tax return, plan for an ongoing annual accrual‑to‑cash adjustment.

The composition of a contractor’s balance sheet at year-end can have a significant impact on taxable income. Changes in receivables, payables, retainage, and other contract-related accounts often drive substantial differences between book income and taxable income. As a result, maintaining a clear understanding of both projected taxable income and the expected accrual-to-cash adjustment is critical for effective tax planning and avoiding year-end surprises.

Facebook
Twitter
LinkedIn

Changes To 2020 Form 1099

Changes to 2020 Form 1099

The IRS has a new Form 1099-NEC to report nonemployee compensation for tax year 2020. The IRS has also revised the Form 1099-MISC and rearranged box numbers for reporting certain income.

If your business has paid $600.00 or more in nonemployee compensation to an unincorporated entity in 2020, you will need to report the payment on Form 1099-NEC. If the payments are for legal services or for medical or health care, they must also be reported to incorporated entities.

If your business has paid $600.00 or more in rent (real property, machinery, or equipment) to an unincorporated entity in 2020, it will need to be reported on Form 1099-MISC. However, you do not have to report these payments on Form 1099-MISC if you paid them to a real estate agent or property manager.

A Form W-9 signed by the vendor should be obtained for each entity that you paid $600.00 or more and will need to report on a Form 1099-NEC or 1099-MISC. If possible, you should obtain a Form W-9 from each vendor that provides a service to your business, at the time of service. A Form W-9 can be downloaded from the IRS website at www.irs.gov.

The due date for filing 2020 Forms 1099-NEC is February 1, 2021. The due date for filing 2020 Forms 1099-MISC is March 1, 2021 for paper-filed returns and March 31, 2021 for electronically filed returns.

We will be glad to assist you with preparation and filing of your 1099s. We can also provide a spreadsheet to help input your information. If you would like for us to prepare your 1099s for you, we will need to receive your information no later than January 18, 2021. Please call us at 251-343-1012 if we can be of assistance.

Crow Shields Bailey PC COVID-19 Response

As we all find ourselves in uncharted territory, we want to share with you how CSB is responding to Coronavirus (COVID-19).

CSB is concerned with the health of our clients, team members, vendors and the communities we serve.

We have a plan in place to ensure continuity of services to our clients.  Our team has the ability to work remotely and can access client information in a safe and secure manner. Whether we are working in our offices or remotely, the lines of communication will remain open.

What you should know:

  • CSB will have drop off boxes in the lobbies of each of our three locations to limit hand-to-hand contact.
  • We will also need to do more phone meetings rather than meeting face-to-face.
  • We will rely on the use of our secure file transfer services such as SafeSend (to electronically receive and sign tax returns) or Sharefile (to send and receive documents which do not require signatures).

Our plan is to have personnel in each of our offices. However, we will follow local regulations and guidance regarding whether an office should be closed.

We value our relationship with you and will continue to provide updates as needed as we navigate these unprecedented times.

Please feel free to reach out with any questions or concerns. We hope you and your loved ones are safe and healthy.


Gina McKellar

Managing Shareholder

Crow Shields Bailey 2020 Promotions

Congratulations to all of our team members that received promotions this year. We are extremely grateful for all of their hard work, and we are proud of them for earning their well-deserved promotions.

Teresa Ernest, CPA was promoted to Principal

Kenny Crow, III, CPA was promoted to Manager

Abby Roveda, CPA was promoted to Supervisor

Jay Crowley, CPA was promoted to Senior Accountant

Allie Parker, CPA was promoted to Senior Accountant

Madison Quigley was promoted to Senior Accountant

Frank Schottgen was promoted to Senior Accountant

The Most Misunderstood Phrase In Accounting

November 19, 2019

Andrew Finnorn | Staff Accountant | Published by Crow Shields Bailey

Throughout the recruitment process, you will hear firms speak of their dedication to a work-life balance. They are referring to the ability to balance the demanding work load of public accounting and life outside the office. It is used as a way to overcome the common belief that public accountants work 24/7. The most important thing to understand is that this challenge must first be overcome at the employee level, then assisted by the firm. This can be accomplished by answering three easy questions.

What are you balancing? The things that you value evolve as you progress through life. When you first enter the workforce as a young adult, time with friends and participating in hobbies are often your main focus. As changes happen, such as marriage or having children, you will find that your priorities and interest will also change. Discovering what is important to you is the first step in creating your ideal work-life balance.

When is the deadline? You will learn very quickly in public accounting that everything revolves around deadlines. There is always another deadline waiting around the corner, and understanding the workload is a key to success. Once you understand the “work” ahead, it allows you to build a schedule that can tackle the sometimes overwhelming workload, and allows for “life.” The anxiety that is felt with approaching deadlines can be mitigated by attacking the work load early. The more work that can be completed on the front end allows you to maintain your desired work-life balance.

Does this firm understand me? With the diversity of the workforce, firms must have an understanding of what is important to each employee. As addressed with the first question, each individual will have different priorities in life. You should search for a firm that aligns with your values. This requires getting to know the firm beyond an interview, and not getting caught up in a recruiting pitch. Current employees and their experiences can often give you an insight into the firm’s values. Look for an opportunity during recruiting events to interview the employees.

As a result of the public’s perception of accountants working 80-hour weeks, the work-life balance has become a point of emphasis for recruitment platforms. Is a work-life balance truly accomplished at the firm level? Yes, they play an important role, but they are only part of the equation. Your understanding of the balancing act and the ability to schedule ahead will allow for the ideal work-life balance in your career.


Six Cliches That Are Still Relevant For Today’s Business Students

September 26, 2019

Abby Roveda, CPA | Senior Accountant | Published by Crow Shields Bailey

Has the statement clichés are clichés for a reason reached cliché status yet? Did that question hurt your brain just a little bit?

At some point in your life, clichés become perceived as the professional equivalent of dad jokes—they’re cheesy and you can hardly ever say them with a straight face. There is still more than an ounce of wisdom to them. In my time in public accounting and working the recruiting circuit, I’ve found that these clichés are still relevant for today’s students.

The Early Bird Catches the Worm

This is NOT about showing up early for interviews and work. This IS about starting to plan for your career now and setting yourself up for the best shot at success. If you don’t know what you want to do yet, you’re not alone. That doesn’t mean that there’s nothing you can do now to prepare for the unknown. Take every opportunity you have to go and hear speakers, attend career fairs, and shadow in different industries until something piques your interest.

If you do know what you want to do, why would you wait for an invitation to start pursuing it? Maybe you’re not at a point academically where it makes sense to do an internship; however, there is no bad time during your college career to attend socials with potential employers, take advantage of job shadowing opportunities, get your resume out there, attend leadership events to add to your resume, or participate in on-campus recruiting. The more a potential employer gets to know you, the less of a hiring risk you become for them.

Fail to prepare, prepare to fail

I do some work on the board of a not-for-profit, and this is the director’s favorite phrase when we have an upcoming event. We spend a lot of time planning for potential mishaps, such as inclement weather or IT problems, and preparing backup plans should any of them actually occur on the day of the event.

How does this apply to students looking for jobs? Have you ever been interviewing for a job and the interviewer asks if you have any questions for them and you replied, “No, I don’t think so?” For many employers, that indicates to them a certain level of disinterest in their company, and even in your own career. Having questions ready for your potential employer is one of the most important steps you can take to prepare for an interview – besides popping a breath mint if you had extra garlic and onions on your pizza at lunch. When you are competing with multiple students for the same job or internship slot, who do you think will have the edge when all other things are considered equal – the one with zero questions for the interviewer or the one with a couple of well-prepared questions?

What doesn’t kill you makes you stronger

Did you just imagine Kelly Clarkson belting that line? Who knew that Kelly was actually singing to business students when she recorded that power ballad?

Being a professional requires you to get out of your comfort zone. There are many aspects of the recruiting process that are just plain unenjoyable. For instance, getting dressed in an uncomfortable suit in the sweltering heat of Alabama, making sweaty handshakes with strangers, repeating the same small talk over and over again…I feel you. I hated career fairs when I was in college. There was not a single aspect of them that I found enjoyable, except that during the height of recruiting season I could usually count on being provided free dinner for 3 of the 5 nights of the week, which was a big help with the old budget. However, by forcing myself to continue to attend these functions, I found that I had actually grown comfortable talking to potential employers. I had become more confident in a room full of strangers and I had actually semi-mastered small talk that didn’t solely revolve around the weather.

Dress for the job you want, not the job you have

Speaking of getting dressed in uncomfortable suits…

Lots of employers have more relaxed dress policies in this day and age. Gone are the days (at most places) of dressing in full suit and tie every day for the office. However, until you know what that dress policy is and until you are actually employed there, you should err on the side of being overdressed. Except for a few exceptions—like showing up for your shift at Habitat for Humanity in a three-piece suit—you will never regret being overdressed in a professional setting. And, even more importantly, your potential employer is not going to note you being overdressed as much as they will if you are underdressed.

You are what you do, not what you say you do

This is really important for when you start working at your first job. However, there is another important spin on this for business students applying for jobs.

My husband has been giving advice to fourth year medical students applying for residency this fall since he just finished the process last year. One of the things we have talked about is the temptation to stack your resume with things that you think make you look good, but don’t necessarily reflect how you actually spend your time or what you value. His advice to fourth year students was, “If you can’t talk about it for 5 minutes, it should not be on your resume.”

What does that mean? You should prepare a 5-minute speech based on everything on your resume? No. If you list a community service activity and it was something you did just to fulfill service hour requirements and not something you actually believed in, do you think you could talk intelligently and passionately about it for 5 minutes if asked about it in an interview? Unless you’re minoring in drama, you probably can’t, and that will lead the employer to question the authenticity of other things listed on your resume as well.

When the going gets tough, the tough get going

If you haven’t experienced a setback at this point in your life, then you probably aren’t challenging yourself. Do you know why employers ask you in interviews to tell them about a time that you failed? Not because they are trying to expose you, but because if you failed, learned something from the experience, and bounced back from it, then you can guarantee that will stand out to them and give you an advantage.

Being a professional in any kind of industry is challenging and you will make mistakes and fail at things multiple times throughout your career. We are counting on it. Not because we like watching you squirm, but because it is absolutely the best way to learn. And if you can’t learn from failure, then there is a limit to what we can teach you.

If you have any questions about career development, recruiting, or any other topic, please feel free to reach out to us. We are always here to help!


CSB Awarded Best Company To Work For By Business Alabama

July 29, 2019

Deborah Fisher | Firm Administrator | Published by Crow Shields Bailey PC

At CSB, our team is our most valuable asset and one of our top priorities is to recruit and retain the best and the brightest. We make sure that team members have a clearly defined career path, mentors to help them reach their goals, opportunities for excellent training, and we have some fun along the way as well.

Because of our “team first” mentality, we were thrilled and honored to discover that the sentiment is mutual when we were named one of Business Alabama Magazine’s Best Companies to Work For. This award is based, in part, on surveys that our team members completed about what it’s like to work here and their satisfaction level with features like benefits, compensation, flexibility, working environment, and more.

We believe that communication is the key to reaching this level of employee satisfaction. We haven’t always been in this position. Just like many other “Boomers” in management, we came up with ideas in meetings that we thought were great and many times, to our dismay, we were not even close to hitting the mark. That’s when we realized that maybe, just maybe, we should actually ask team members what would make CSB a great place to work.

We took great pride in having an “open door policy” but sometimes that simply meant listening to suggestions. If you don’t take action, then what’s the point?  We began to really listen to team members’ ideas and started taking action. As a result, for the last eight years or so, our team is responsible for many changes such as our dress code (we now have a Dress for Your Day policy), recruiting (our team plans and executes events), community service (we vote on our main charity each year), compensation (our team is responsible for various changes to our compensation structure), time off policy (we ditched traditional “vacation and sick leave” and replaced with PTO), two extra holidays came from team recommendations, and the list goes on.

In summary, if you are putting forth the effort to hire and retain the best and the brightest – let them show you what they can do. We firmly believe that the change in our mindset to move from just listening to listening AND taking action is one of the reasons that we have been named one of the best companies to work for in Alabama. And for that, we are truly grateful.


Kristi Daughtery Wins Best CPA in 2019 Nappie Awards

CSB is proud to announce that our very own Kristi Daughtery received the 2019 Nappie Award for Best CPA! We can’t think of anyone more deserving and are glad the city of Mobile and those on the Eastern Shore agree. We appreciate the thousands of Lagniappe readers in Mobile and Baldwin Counties who voted for their favorite hometown heroes and recognized a member of the CSB team for the second year in a row. Kristi is the definition of what “reaching beyond the numbers” means and she inspires us all to be the best we can be. Congratulations to Kristi!

Accounting Students – Should You Choose Tax or Audit?

June 19, 2019

Caitlyn Grimme, CPA | Supervisor | Published by Crow Shields Bailey PC

One of the biggest decisions an accountant will face is the choice to specialize in tax or audit.  While this decision may come easily to some, for others it can be the most difficult choice of their career.

Tax vs. Audit – What’s the Difference?

While both are accounting professions, the tax and audit paths can vary greatly.   In the tax division, your day will focus on trying to reduce the client’s tax liability.  Meanwhile, the purpose of an audit is to express an opinion as to whether the financial statements of a company are free from material misstatement. As such, auditors devise testing measures and scopes to evaluate the information provided by the client in order to express an opinion.  Additionally, auditors may also work on other forms of attestation engagements such as reviews and compilations, which provide limited to no assurance regarding the financial statements.

Both tax and audit are rules and research based. Tax professionals must comply with rules set by the Internal Revenue Service and The U.S. Securities and Exchange Commission. Auditors must also follow generally accepted accounting principles (GAAP), generally accepted auditing standards (GAAS), additional SEC and PCAOB guidelines if required, as well as certain industry-specific guidance.  However, while auditors rely on research and rules, they also rely heavily on auditor judgment.

Audit professionals must have strong interpersonal communication skills, as you are onsite communicating with clients on a daily basis.  Tax professionals typically work in the firm office and might not communicate directly with a client for several months.

Both career paths are now heavily dependent on computer and software applications, so regardless of your choice, proficiency in technology is important.

There is conflicting information from online sources regarding differences in pay for auditors vs. tax professionals.  Some sites state that lower level audit staff jobs are more plentiful than tax staff positions starting out and might offer higher initial pay.  However, other sites argue that tax professionals have higher initial earning power. At the end of day, I would recommend choosing the path that you are more passionate about, as the earning potential doesn’t appear drastically different for either course (note this may vary by firm, industry specialization, etc.).

Are There Pros and Cons to Each Path?

Although not every firm is the same, here are a few standard pros and cons:

Audit:

Pros:

  • Travel – audit professionals typically spend less time in the firm office than tax professionals. Whether the travel is local, regional, or national can depend on the specific accounting firm.  For instance, audit professionals at large regional or national firms might spend a significant amount of time traveling while professionals at local firms might travel primarily to clients in their area.  Independent of firm size, boutique firms specializing in a specific industry might travel more than others.  If you like a varied day/routine with occasional to frequent travel, audit might be a good fit for you.
  • Steady work flow – while the tax profession is driven by statutory deadlines, audit work is more consistent and constant throughout the year. There are still deadlines in the audit world, but these deadlines (which are usually set by governing bodies such as a board of directors or third parties such as bankers or bonding agencies) are usually spread more evenly throughout the year.
  • Teamwork – audit engagements typically consist of an “audit team” with a partner, manager/in-charge, and staff member, at the least. This environment yields itself to mentorship and in-the-field hands-on learning for those new to the profession.
  • Client interaction – with audit, a large portion of the engagement is performed “in the field” (i.e. at the client’s office). As a result, staff will be interacting with client personnel ranging from accounting clerks to the CEO on a daily basis.

Cons:

  • Travel – while travel might appeal to some, it might be a significant deterrent to others. It is important when interviewing for an audit internship or staff position to question the firm’s expectation regarding amount of time spent traveling, as it can range by firm size or specialization as noted above.
  • Professional skepticism – attestation engagements require independence from the client. This can be a problem for professionals who get too involved in order to “help” the client, as it can lead the auditor to making management decisions for the client and impairing independence and objectivity.

Tax:

Pros:

  • Deadline-driven – while the time surrounding tax deadlines can typically be very busy for CPAs in the tax department, there is usually a lull between these storms that provides plenty of time for vacation, continuing education, professional development, etc.
  • Independent work – while the audit department works on a team, tax professionals have more opportunity for independent work. While there is always someone available for questions if needed, if you prefer to work on projects on your own, then tax might be a better fit.
  • Fast turn-around – while audits may drag out for weeks or months, tax returns are usually much smaller individual engagements which lead to quicker turnaround. If you are someone who likes to quickly cross projects off your list, this might be the path for you.
  • Exposure – although you are not in the field with the client on a daily basis as in auditing, tax professionals receive more exposure to different clients throughout the year. For example, an auditor might work directly with 10-15 clients a year, while a tax professional might deal with 100.

Cons:

  • Deadlines – while the lull provided after a deadline is nice, the weeks and months leading up to a deadline require overtime work by tax professionals, which dissuades many from joining the profession.
  • Client exposure – since tax professionals work primarily in the office, they do not interact face-to-face with clients daily. This could be preferred if you tend to be more introverted, but extroverts might find this arrangement challenging.

I’m Still Undecided – What Can I Do?

If you are still unsure which path is a better fit, try out some of the following:

Apply for an internship – internships are a fantastic way to learn the basics of both disciplines.  Most large firms will offer internship experience on a tax or audit basis which allows full immersion in either path.  Smaller local firms may offer internship opportunities with exposure to both tax and audit in the same internship round (typically a “busy season” internship from January through April 15th).

Online forums – in the age of technology we live in, information is at the tips of our fingers, literally.  There are several sites with forum posts or resources surrounding this subject.  Check out the CPA exam forum on www.another71.com or the AICPA career guidance section, just to name a few.

Ultimately, the career you choose must be the best fit for you.  What are pros for one person might be cons for another (ex. frequency of travel engagements).  However, as long as you know yourself and what is most important to you, you will make the right decision.  Feel free to contact us to set up a job shadowing appointment if you would like to get a glimpse at a normal day for tax and audit professionals.